CRR › Article 308
Article 308 Own funds requirements for pre-funded contributions to the default fund of a QCCP
official text, verbatim
The exposure value for an institution's pre-funded contribution to the default fund of a QCCP (DFi) shall be the amount paid in or the market value of the assets delivered by that institution reduced by any amount of that contribution that the QCCP has already used to absorb its losses following the default of one or more of its clearing members.
An institution shall calculate the own funds requirement to cover the exposure arising from its pre-funded contribution as follows:
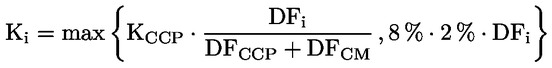
where:
| Ki | = | the own funds requirement; |
| i | = | the index denoting the clearing member; |
| KCCP | = | the hypothetical capital of the QCCP communicated to the institution by the QCCP in accordance with Article 50c of Regulation (EU) No 648/2012; |
| DFi | = | the pre-funded contribution; |
| DFCCP | = | the pre-funded financial resources of the CCP communicated to the institution by the CCP in accordance with Article 50c of Regulation (EU) No 648/2012; and |
| DFCM | = | the sum of pre-funded contributions of all clearing members of the QCCP communicated to the institution by the QCCP in accordance with Article 50c of Regulation (EU) No 648/2012. |
An institution shall calculate the risk-weighted exposure amounts for exposures arising from that institution's pre-funded contribution to the default fund of a QCCP for the purposes of Article 92(3) as the own funds requirement, calculated in accordance with paragraph 2 of this Article, multiplied by 12,5.