CRR › Article 325bd
Article 325bd Liquidity horizons
official text, verbatim
Institutions shall map each risk factor of positions assigned to the trading desks for which they have been granted permission as referred to in Article 325az(2), or for which they are in the process of being granted such permission, to one of the broad categories of risk factors listed in Table 2 and to one of the broad sub-categories of risk factors listed in that Table.
The liquidity horizon of a risk factor of the positions referred to in paragraph 1 shall be the liquidity horizon of the corresponding broad sub-category of risk factors to which it has been mapped.
By way of derogation from paragraph 1 of this Article, for a given trading desk, an institution may decide to replace the liquidity horizon of a broad sub-category of risk factors listed in Table 2 of this Article with one of the longer liquidity horizons listed in Table 1 of Article 325bc. Where an institution takes such a decision, the longer liquidity horizon shall apply to all the modellable risk factors of the positions assigned to that trading desk that have been mapped to that broad sub-category of risk factors for the purpose of calculating the partial expected shortfall measures in accordance with point (c) of Article 325bc(1).
An institution shall notify the competent authorities of the trading desks and the broad sub-categories of risk factors to which it decides to apply the treatment referred to in the first subparagraph.
For the purpose of calculating the partial expected shortfall measures in accordance with point (c) of Article 325bc(1), the effective liquidity horizon of a given modellable risk factor of a given trading book position or a non-trading book position that is subject to foreign exchange or commodity risk shall be calculated as follows:
| EffectiveLH = | 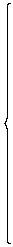 | SubCatLH if Mat > LH5 |
| min (SubCatLH, minj{LHj/LHj ≥ Mat}) if LH1 ≤ Mat ≤ LH5 | ||
| LH1 if Mat < LH1 |
where:
| EffectiveLH | = | the effective liquidity horizon; |
| Mat | = | the maturity of the trading book position; |
| SubCatLH | = | the length of liquidity horizon of the modellable risk factor determined in accordance with paragraph 1; and |
| minj {LHj/LHj ≥ Mat} | = | the length of one of the liquidity horizons listed in Table 1 of Article 325bc which is the nearest liquidity horizon above the maturity of the trading book position. |
Currency pairs that are composed of the euro and the currency of a Member State participating in ERM II shall be included in the most liquid currency pairs sub-category within the broad category of foreign exchange risk factor of Table 2.
Currencies of Member States participating in ERM II shall be included in the most liquid currencies and domestic currency sub-category within the broad category of interest rate risk factor of Table 2.
An institution shall verify the appropriateness of the mapping referred to in paragraph 1 on at least a monthly basis.
EBA shall develop draft regulatory technical standards to specify:
how institutions are to map the risk factors of the positions referred to in paragraph 1 to broad categories of risk factors and broad sub-categories of risk factors for the purposes of paragraph 1;
which currencies constitute the most liquid currencies sub-category of the broad category of interest rate risk factor of Table 2;
which currency pairs constitute the most liquid currency pairs sub-category of the broad category of foreign exchange risk factor of Table 2;
the definitions of small market capitalisation and large market capitalisation for the purposes of the equity price and volatility sub-category of the broad category of equity risk factor of Table 2.
EBA shall submit those draft regulatory technical standards to the Commission by 28 March 2020.
Power is delegated to the Commission to supplement this Regulation by adopting the regulatory technical standards referred to in the first subparagraph in accordance with Articles 10 to 14 of Regulation (EU) No 1093/2010.
Table 2
| Broad categories of risk factors | Broad sub-categories of risk factors | Liquidity horizons | Length of the liquidity horizon (in days) |
| Interest rate | Most liquid currencies and domestic currency | 1 | 10 |
| Other currencies (excluding most liquid currencies) | 2 | 20 | |
| Volatility | 4 | 60 | |
| Other types | 4 | 60 | |
| Credit spread | Central government, including central banks, of Member States | 2 | 20 |
| Covered bonds issued by credit institutions in Member States (Investment Grade) | 2 | 20 | |
| Sovereign (Investment grade) | 2 | 20 | |
| Sovereign (High yield) | 3 | 40 | |
| Corporate (Investment grade) | 3 | 40 | |
| Corporate (High yield) | 4 | 60 | |
| Volatility | 5 | 120 | |
| Other types | 5 | 120 | |
| Equity | Equity price (Large market capitalisation) | 1 | 10 |
| Equity price (Small market capitalisation) | 2 | 20 | |
| Volatility (Large market capitalisation) | 2 | 20 | |
| Volatility (Small market capitalisation) | 4 | 60 | |
| Other types | 4 | 60 | |
| Foreign exchange | Most liquid currency pairs | 1 | 10 |
| Other currency pairs (excluding most liquid currency pairs) | 2 | 20 | |
| Volatility | 3 | 40 | |
| Other types | 3 | 40 | |
| Commodity | Energy price and carbon emissions price | 2 | 20 |
| Precious metal price and non-ferrous metal price | 2 | 20 | |
| Other commodity prices (excluding energy price, carbon emissions price, precious metal price and non-ferrous metal price) | 4 | 60 | |
| Energy volatility and carbon emissions volatility | 4 | 60 | |
| Precious metal volatility and non-ferrous metal volatility | 4 | 60 | |
| Other commodity volatilities (excluding energy volatility, carbon emissions volatility, precious metal volatility and non-ferrous metal volatility) | 5 | 120 | |
| Other types | 5 | 120 |