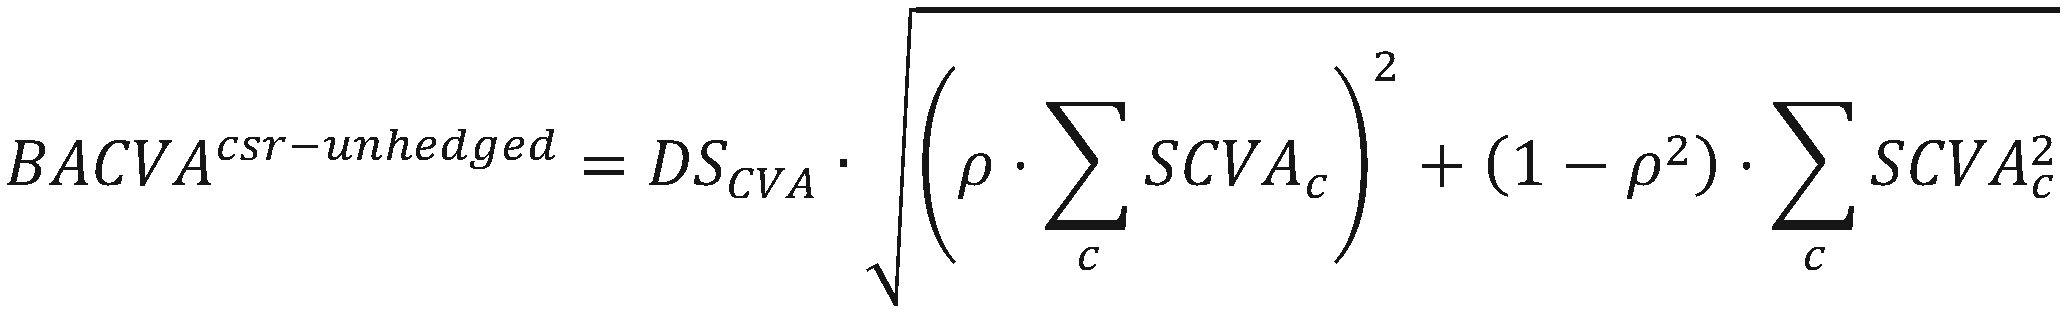An institution that meets the condition referred to in paragraph 1, point (a), shall calculate the own funds requirements for CVA risk as follows:
BACVAtotal = β · BACVAcsr–unhedged + DSCVA · (1 – β) · BACVAcsr–hedged
where:
| BACVAtotal | = the own funds requirements for CVA risk under the basic approach; |
| BACVAcsr–unhedged | = the own funds requirements for CVA risk under the basic approach as calculated in accordance with paragraph 3 for an institution that meets the condition set out in paragraph 1, point (b); |
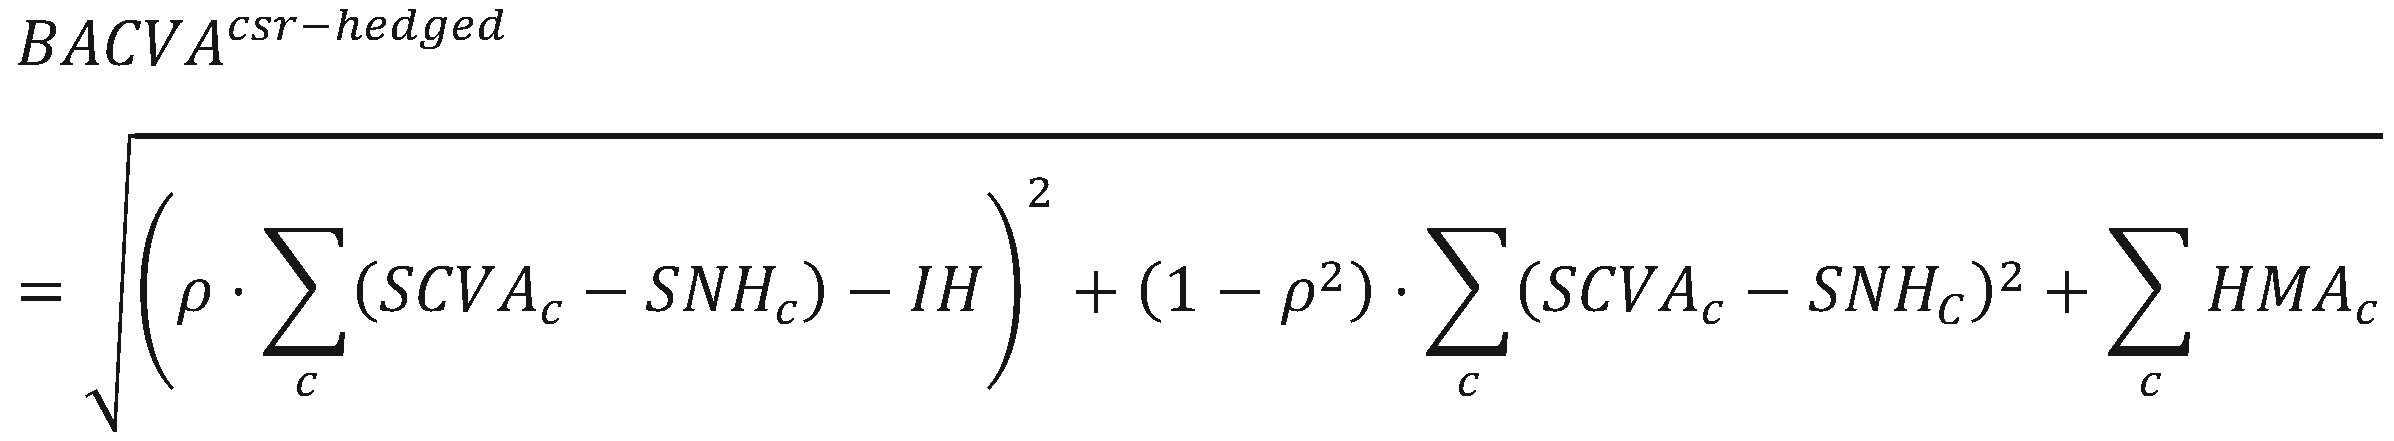
where:
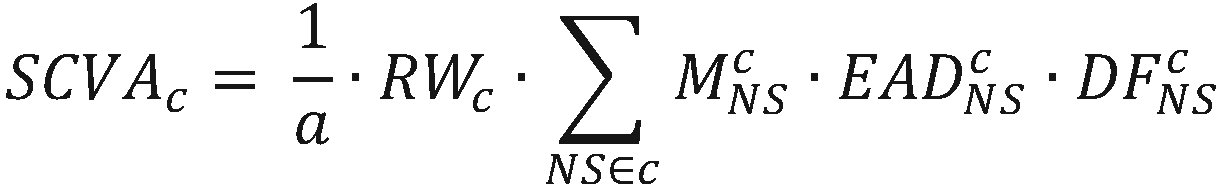
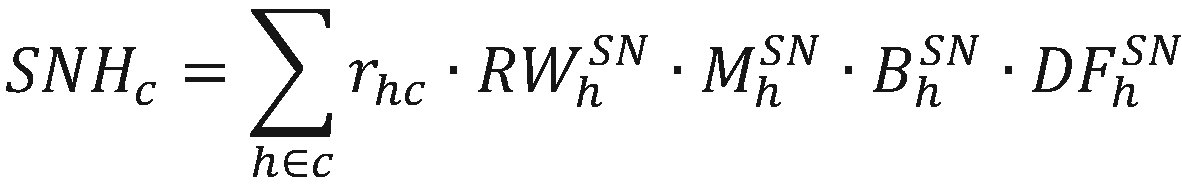
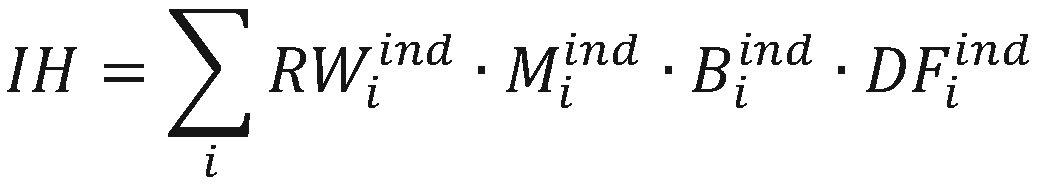
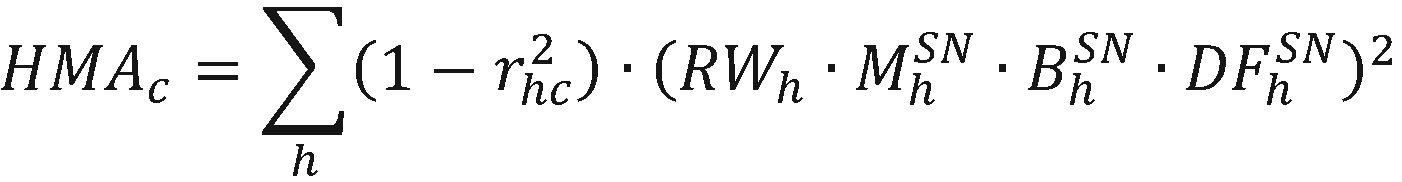
| c | = the index that denotes all counterparties for which the institution calculates the own funds requirements for CVA risk using the approach laid down in this Article; |
| NS | = the index that denotes all netting sets with a given counterparty for which the institution calculates the own funds requirements for CVA risk using the approach laid down in this Article; |
| h | = the index that denotes all single-name instruments recognised as eligible hedges in accordance with Article 386 for a given counterparty for which the institution calculates the own funds requirements for CVA risk using the approach laid down in this Article; |
| I | = the index that denotes all index instruments recognised as eligible hedges in accordance with Article 386 for all counterparties for which the institution calculates the own funds requirements for CVA risk using the approach laid down in this Article; |
| RWc | = the risk weight applicable to counterparty c; counterparty c shall be mapped to one of the risk weights based on a combination of sector and credit quality and determined in accordance with Table 1. |
Where there are no external ratings for a specific counterparty, institutions may, subject to approval by the competent authorities, map the internal rating to a corresponding external rating and assign a risk weight corresponding to either credit quality step 1 to 3 or credit quality step 4 to 6; otherwise, the risk weights for unrated exposures shall be applied.
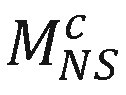 = the effective maturity for the netting set NS with counterparty c;
shall be calculated in accordance with Article 162; however, for that calculation, shall not be capped at five years, but at the longest contractual remaining maturity in the netting set;
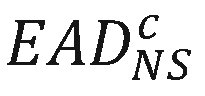 | = the counterparty credit risk exposure value of the netting set NS with counterparty c, including the effect of collateral in accordance with the methods set out in Title II, Chapter 6, Sections 3 to 6, as applicable to the calculation of the own funds requirements for counterparty credit risk referred to in Article 92(4), points (a) and (g); |
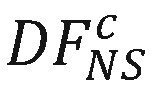 | = the supervisory discount factor for the netting set NS with counterparty c. |
For an institution, using the methods set out in Title II, Chapter 6, Section 6, the supervisory discount factor shall be set at 1; in all other cases, the supervisory discount factor shall be calculated as follows:
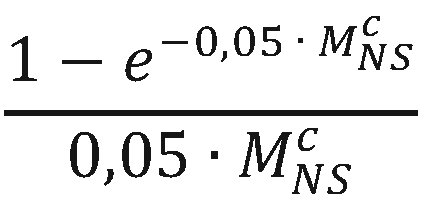
| rhc | = the supervisory correlation factor between the credit spread risk of counterparty c and the credit spread risk of a single-name instrument recognised as an eligible hedge h for counterparty c, determined in accordance with Table 2; |
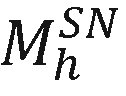 | = the residual maturity of a single-name instrument recognised as an eligible hedge; |
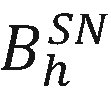 | = the notional of a single name instrument recognised as an eligible hedge; |
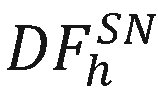 | = the supervisory discount factor for a single name instrument recognised as an eligible hedge, calculated as follows: 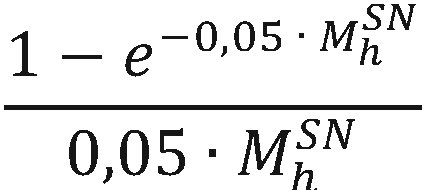 |
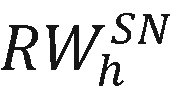 | = the supervisory risk weight of a single-name instrument recognised as an eligible hedge; those risk weights shall be based on a combination of sector and credit quality of the reference credit spread of the hedging instrument and determined in accordance with Table 1; |
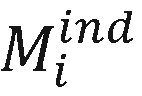 | = the residual maturity of one or more positions in the same index instrument recognised as an eligible hedge; in the case of more than one position in the same index instrument, shall be the notional-weighted maturity of all those positions; |
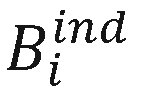 | = the full notional of one or more positions in the same index instrument recognised as an eligible hedge; |
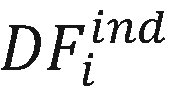 | = the supervisory discount factor for one or more positions in the same index instrument recognised as an eligible hedge, calculated as follows: 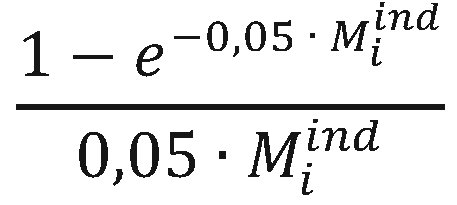 |
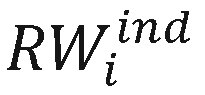 | = the supervisory risk weight of an index instrument recognised as an eligible hedge; shall be based on a combination of sector and credit quality of all index constituents, calculated as follows: (a) where all index constituents belong to the same sector and have the same credit quality, as determined in accordance with Table 1, shall be calculated as the relevant risk weight of Table 1 for that sector and credit quality multiplied by 0,7 ; (b) where all index constituents do not belong to the same sector or do not have the same credit quality, shall be calculated as a weighted average of the risk weights of all index constituents, as determined in accordance with Table 1, multiplied by 0,7 ; |