CRR › Article 263
Article 263 Calculation of risk-weighted exposure amounts under the External Ratings Based Approach (SEC-ERBA)
official text, verbatim
Under the SEC-ERBA, the risk-weighted exposure amount for a securitisation position shall be calculated by multiplying the exposure value of the position as calculated in accordance with Article 248 by the applicable risk weight in accordance with this Article.
For exposures with short-term credit assessments or when a rating based on a short-term credit assessment may be inferred in accordance with paragraph 7, the following risk weights shall apply:
Table 1
| Credit Quality Step | 1 | 2 | 3 | All other ratings |
| Risk weight | 15 % | 50 % | 100 % | 1 250 % |
For exposures with long-term credit assessments or when a rating based on a long-term credit assessment may be inferred in accordance with paragraph 7 of this Article, the risk weights set out in Table 2 shall apply, adjusted as applicable for tranche maturity (MT) in accordance with Article 257 and paragraph 4 of this Article and for tranche thickness for non-senior tranches in accordance with paragraph 5 of this Article:
Table 2
| Credit Quality Step | Senior tranche | Non-senior (thin) tranche |
| Tranche maturity (MT) | Tranche maturity (MT) |
| 1 year | 5 years | 1 year | 5 years |
| 1 | 15 % | 20 % | 15 % | 70 % |
| 2 | 15 % | 30 % | 15 % | 90 % |
| 3 | 25 % | 40 % | 30 % | 120 % |
| 4 | 30 % | 45 % | 40 % | 140 % |
| 5 | 40 % | 50 % | 60 % | 160 % |
| 6 | 50 % | 65 % | 80 % | 180 % |
| 7 | 60 % | 70 % | 120 % | 210 % |
| 8 | 75 % | 90 % | 170 % | 260 % |
| 9 | 90 % | 105 % | 220 % | 310 % |
| 10 | 120 % | 140 % | 330 % | 420 % |
| 11 | 140 % | 160 % | 470 % | 580 % |
| 12 | 160 % | 180 % | 620 % | 760 % |
| 13 | 200 % | 225 % | 750 % | 860 % |
| 14 | 250 % | 280 % | 900 % | 950 % |
| 15 | 310 % | 340 % | 1 050 % | 1 050 % |
| 16 | 380 % | 420 % | 1 130 % | 1 130 % |
| 17 | 460 % | 505 % | 1 250 % | 1 250 % |
| All other | 1 250 % | 1 250 % | 1 250 % | 1 250 % |
In order to determine the risk weight for tranches with a maturity between 1 and 5 years, institutions shall use linear interpolation between the risk weights applicable for 1 and 5 years maturity respectively in accordance with Table 2.
In order to account for tranche thickness, institutions shall calculate the risk weight for non-senior tranches as follows:
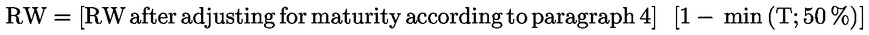
where
T = tranche thickness measured as D – A
where
| D | is the detachment point as determined in accordance with Article 256 |
| A | is the attachment point as determined in accordance with Article 256 |
The risk weights for non-senior tranches resulting from paragraphs 3, 4 and 5 shall be subject to a floor of 15 %. In addition, the resulting risk weights shall be no lower than the risk weight corresponding to a hypothetical senior tranche of the same securitisation with the same credit assessment and maturity.
For the purposes of using inferred ratings, institutions shall attribute to an unrated position an inferred rating equivalent to the credit assessment of a rated reference position which meets all of the following conditions:
the reference position ranks pari passu in all respects to the unrated securitisation position or, in the absence of a pari passu ranking position, the reference position is immediately subordinate to the unrated position;
the reference position does not benefit from any third-party guarantees or other credit enhancements that are not available to the unrated position;
the maturity of the reference position shall be equal to or longer than that of the unrated position in question;
on an ongoing basis, any inferred rating shall be updated to reflect any changes in the credit assessment of the reference position.
Where an institution has a securitisation position in the form of a derivative to hedge market risks, including interest rate or currency risks, the institution may attribute to that derivative an inferred risk weight equivalent to the risk weight of the reference position calculated in accordance with this Article.
For the purposes of the first subparagraph, the reference position shall be the position that is pari passu in all respects to the derivative or, in the absence of such pari passu position, the position that is immediately subordinate to the derivative.