CRR › Article 252
Article 252 Treatment of maturity mismatches in synthetic securitisations
official text, verbatim
For the purposes of calculating risk-weighted exposure amounts in accordance with Article 251, any maturity mismatch between the credit protection by which the transfer of risk is achieved and the underlying exposures shall be calculated as follows:
the maturity of the underlying exposures shall be taken to be the longest maturity of any of those exposures subject to a maximum of 5 years. The maturity of the credit protection shall be determined in accordance with Chapter 4;
an originator institution shall ignore any maturity mismatch in calculating risk-weighted exposure amounts for securitisation positions subject to a risk weight of 1 250 % in accordance with this Section. For all other positions, the maturity mismatch treatment set out in Chapter 4 shall be applied in accordance with the following formula:
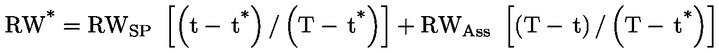
where:
| RW* | = | risk-weighted exposure amounts for the purposes of Article 92(4), point (a); |
| RWAss | = | risk-weighted exposure amounts for the underlying exposures as if they had not been securitised, calculated on a pro-rata basis; |
| RWSP | = | risk-weighted exposure amounts calculated under Article 251 as if there was no maturity mismatch; |
| T | = | maturity of the underlying exposures, expressed in years; |
| t | = | maturity of credit protection, expressed in years; |
| t* | = | 0,25 |