CRR › Article 325ad
Article 325ad Calculation of the own funds requirements for the default risk for the ACTP
official text, verbatim
1
Net JTD amounts shall be multiplied by:
1(a)
for non-tranched products, the default risk weights corresponding to their credit quality as specified in Article 325y(1) and (2);
1(b)
for tranched products, the default risk weights referred to in Article 325aa(1).
2
Risk-weighted net JTD amounts shall be assigned to buckets that correspond to an index.
3
Weighted net JTD amounts shall be aggregated within each bucket in accordance with the following formula:
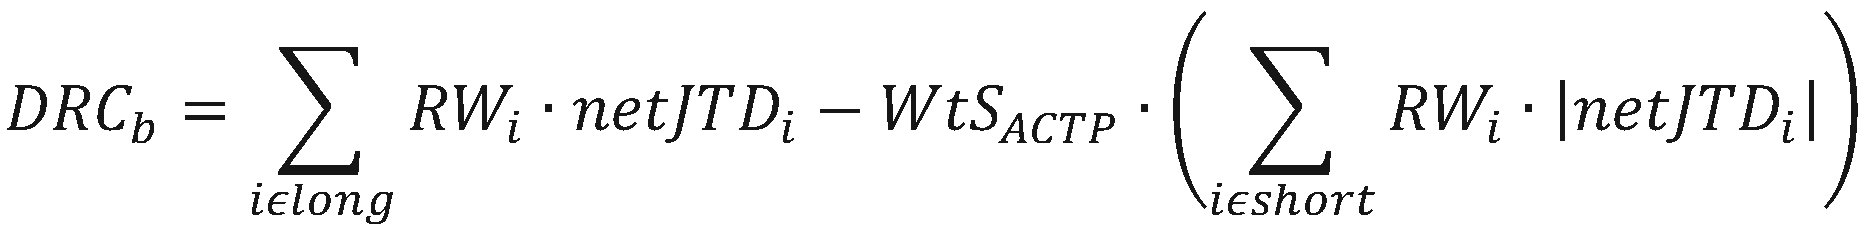
where:
| DRCb | = | the own funds requirement for the default risk for bucket b; |
| i | = | an instrument belonging to bucket b; and |
| WtSACTP | = | the ratio recognising a benefit for hedging relationships within a bucket, which shall be calculated in accordance with the WtS formula set out in Article 325y(4), but using long positions and short positions across the entire ACTP and not just the positions in the particular bucket. |
4
Institutions shall calculate the own funds requirements for the default risk for the ACTP by using the following formula:
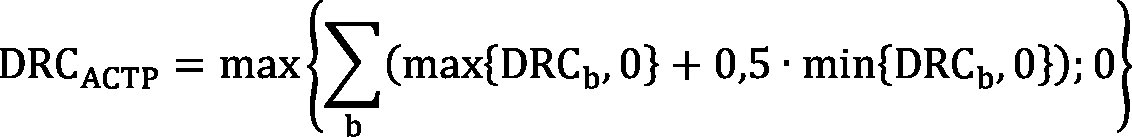
where:
| DRCACTP | = | the own funds requirement for the default risk for the ACTP; and |
| DRCb | = | the own funds requirement for the default risk for bucket b. |