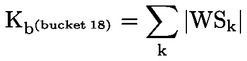CRR › Article 325ai
Article 325ai Intra-bucket correlations for credit spread risk for non-securitisations
official text, verbatim
The correlation parameter ρk l between two sensitivities WS k and WS l within the same bucket shall be set as follows:
ρkl = ρkl (name) · ρkl (tenor) · ρkl (basis)
where:
ρkl (name) shall be equal to 1 where the two names of sensitivities k and l are identical; it shall be equal to 35 % where the two names of sensitivities k and l are in buckets 1 to 18 in Article 325ah(1), Table 4, otherwise it shall be equal to 80 %;
ρkl (tenor) shall be equal to 1 where the two vertices of the sensitivities k and l are identical, otherwise it shall be equal to 65 %; and
ρkl (basis) shall be equal to 1 where the two sensitivities are related to the same curves, otherwise it shall be equal to 99,90 %.
The correlation parameters referred to in paragraph 1 of this Article shall not apply to bucket 18 in Table 4 of Article 325ah(1). The capital requirement for the delta risk aggregation formula within bucket 18 shall be equal to the sum of the absolute values of the net weighted sensitivities allocated to that bucket: