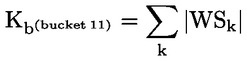CRR › Article 325aq
Article 325aq Intra-bucket correlations for equity risk
official text, verbatim
The delta risk correlation parameter ρkl between two sensitivities WS k and WS l within the same bucket shall be set at 99,90 % where one is a sensitivity to an equity spot price and the other is a sensitivity to an equity repo rate and where both sensitivities are related to the same equity issuer name.
In other cases than the cases referred to in paragraph 1, the correlation parameter ρkl between two sensitivities WS k and WS l to equity spot price within the same bucket shall be set as follows:
15 % between two sensitivities within the same bucket that fall under the category large market capitalisation, emerging market economy (bucket number 1, 2, 3 or 4);
25 % between two sensitivities within the same bucket that fall under the category large market capitalisation, advanced economy (bucket number 5, 6, 7 or 8);
7,5 % between two sensitivities within the same bucket that fall under the category small market capitalisation, emerging market economy (bucket number 9);
12,5 % between two sensitivities within the same bucket that fall under the category small market capitalisation, advanced economy (bucket number 10);
80 % between two sensitivities within the same bucket that fall under either index bucket (bucket number 12 or 13).
The correlation parameter ρkl between two sensitivities WSk and WSl to equity repo rates within the same bucket shall be set in accordance with points (a) to (d) of paragraph 2.
Between two sensitivities WS k and WS l within the same bucket where one is a sensitivity to an equity spot price and the other a sensitivity to an equity repo rate and both sensitivities relate to a different equity issuer name, the correlation parameter ρkl shall be set to the correlation parameters specified in paragraph 2, multiplied by 99,90 %.
The correlation parameters specified in paragraphs 1 to 4 shall not apply to bucket 11. The capital requirement for the delta risk aggregation formula within bucket 11 shall be equal to the sum of the absolute values of the net weighted sensitivities allocated to that bucket: