CRR › Article 220
Article 220 Using the Supervisory Volatility Adjustments Approach for master netting agreements
official text, verbatim
Institutions that calculate the ‘fully adjusted exposure value’ (E*) for the exposures subject to an eligible master netting agreement covering securities financing transactions or other capital market-driven transactions shall calculate the volatility adjustments that they need to apply by using the Supervisory Volatility Adjustments Approach set out in Articles 223 to 227 for the Financial Collateral Comprehensive Method.
For the purpose of calculating E*, institutions shall:
calculate the net position in each group of securities or in each type of commodity by subtracting the amount in point (ii) from the amount in point (i):
the total value of a group of securities or of commodities of the same type lent, sold or provided under the master netting agreement;
the total value of a group of securities or of commodities of the same type borrowed, purchased or received under the master netting agreement;
calculate the net position in each currency, other than the settlement currency of the master netting agreement, by subtracting the amount in point (ii) from the amount in point (i):
the sum of the total value of securities denominated in that currency lent, sold or provided under the master netting agreement and the amount of cash in that currency lent or transferred under that agreement;
the sum of the total value of securities denominated in that currency borrowed, purchased or received under the master netting agreement and the amount of cash in that currency borrowed or received under that agreement;
apply the value of the volatility adjustment, or, where relevant, the absolute value of the volatility adjustment appropriate for a given group of securities or for a given type of commodities, to the absolute value of the positive or negative net position in the securities in that group of securities, or to the commodities from that type of commodities;
apply the foreign exchange risk (fx) volatility adjustment to the net positive or negative position in each currency other than the settlement currency of the master netting agreement.
Institutions shall calculate E* in accordance with the following formula:
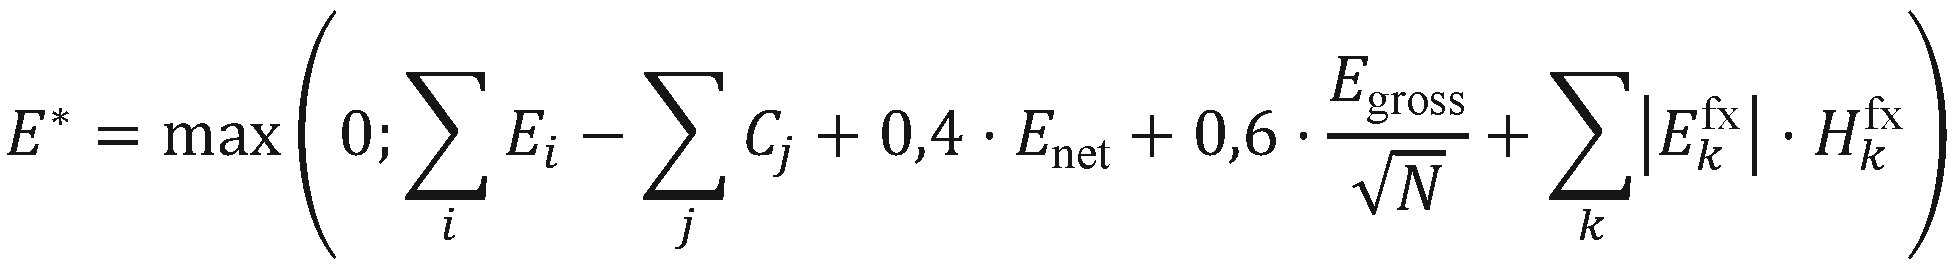
where:
| i | = the index that denotes all separate securities, commodities or cash positions under the agreement that are either lent, sold with an agreement to repurchase, or posted by the institution to the counterparty; |
| j | = the index that denotes all separate securities, commodities or cash positions under the agreement that are either borrowed, purchased with an agreement to resell, or held by the institution; |
| k | = the index that denotes all separate currencies in which any securities, commodities or cash positions under the agreement are denominated; |
| Ei | = the exposure value of a given security, commodity or cash position i, that is either lent, sold with an agreement to repurchase, or posted to the counterparty under the agreement that would apply in the absence of credit protection, where institutions calculate the risk-weighted exposure amounts in accordance with Chapter 2 or 3, as applicable; |
| Cj | = the value of a given security, commodity or cash position j that is either borrowed, purchased with an agreement to resell, or held by the institution under the agreement; |
 | = the net position (positive or negative) in a given currency k other than the settlement currency of the agreement as calculated in accordance with paragraph 2, point (b); |
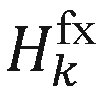 | = the foreign exchange volatility adjustment for currency k; |
| Enet | = the net exposure of the agreement, calculated as follows: |
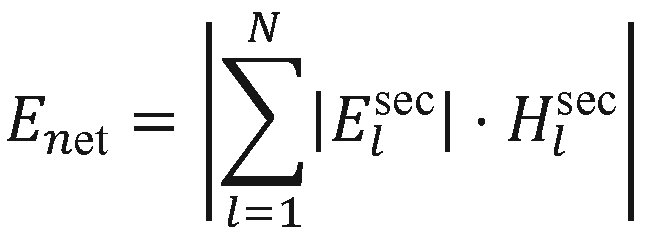
where:
| l | = the index that denotes all distinct groups of the same securities and all distinct types of the same commodities under the agreement; |
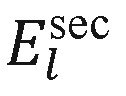 | = the net position (positive or negative) in a given group of securities l, or a given type of commodities l, under the agreement, calculated in accordance with paragraph 2, point (a); |
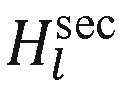 | = the volatility adjustment appropriate to a given group of securities l, or a given type of commodities l, determined in accordance with paragraph 2, point (c); the sign of shall be determined as follows: (a) it shall have a positive sign where the group of securities l is lent, sold with an agreement to repurchase, or transacted in a manner similar to either a securities lending or a repurchase agreement; (b) it shall have a negative sign where the group of securities l is borrowed, purchased with an agreement to resell, or transacted in a manner similar to either a securities borrowing or a reverse repurchase agreement; |
| N | = the total number of distinct groups of the same securities and distinct types of the same commodities under the agreement; for the purposes of this calculation, those groups and types for which 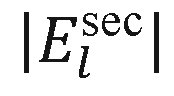 is less than 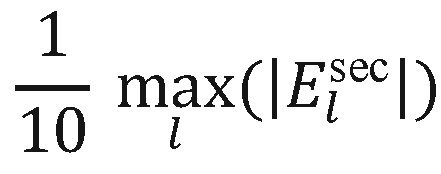 shall not be counted; |
| Egross | = the gross exposure of the agreement, calculated as follows: |
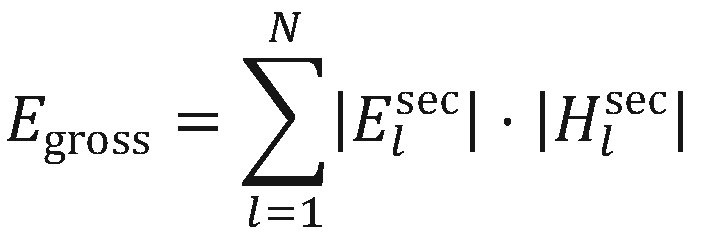 .
For the purpose of calculating risk-weighted exposure amounts and expected loss amounts for repurchase transactions or securities or commodities lending or borrowing transactions or other capital market-driven transactions covered by master netting agreements, institutions shall use E* as calculated under paragraph 3 as the exposure value of the exposure to the counterparty arising from the transactions subject to the master netting agreement for the purposes of Article 113 under the Standardised Approach or Chapter 3 under the IRB Approach.
For the purposes of paragraphs 2 and 3, ‘group of securities’ means securities which are issued by the same entity, have the same issue date, the same maturity, are subject to the same terms and conditions, and are subject to the same liquidation periods as indicated in Articles 224 and 225, as applicable.