CRR › Article 231
Article 231 Calculating risk-weighted exposure amounts and expected loss amounts in the case of pools of eligible funded credit protection for an exposure treated under the IRB Approach
official text, verbatim
Institutions that have obtained multiple types of funded credit protection may, for exposures treated under the IRB Approach, apply the formula set out in Article 230, sequentially for each individual type of collateral. For that purpose, those institutions shall, after each step of recognising one individual type of FCP, reduce the remaining value of the unsecured exposure (EU) by the adjusted value of the collateral (ES) recognised in that step. In accordance with Article 230(1), the total of ES across all funded credit protection types shall be capped at the value of E·(1+HE), resulting in the following formula:
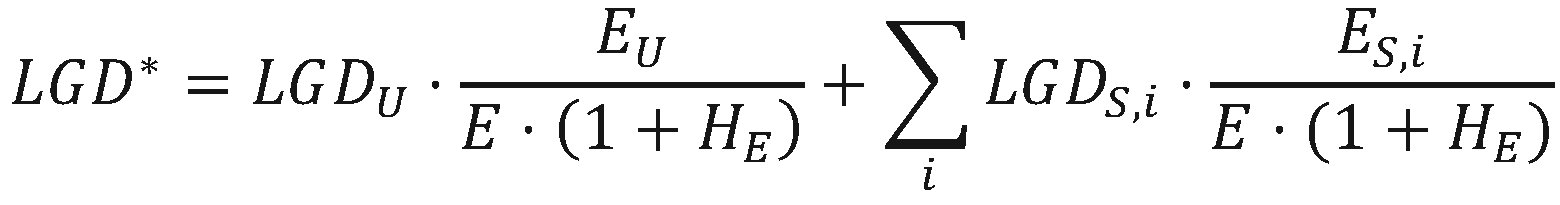
where:
| LGDS,i | = the LGD applicable to FCP i, as specified in Article 230(2); |
| ES,i | = the current value of FCP i received after the application of the volatility adjustment applicable for the type of FCP (Hc) pursuant to Article 230(2). |