CRR › Article 233
Article 233 Valuation
official text, verbatim
For the purpose of calculating the effects of unfunded credit protection in accordance with this Sub-section, the value of unfunded credit protection (G) shall be the amount that the protection provider has undertaken to pay in the event of the default or non-payment of the borrower or on the occurrence of other specified credit events.
In the case of credit derivatives which do not include as a credit event restructuring of the underlying obligation involving forgiveness or postponement of principal, interest or fees that result in a credit loss event the following shall apply:
where the amount that the protection provider has undertaken to pay is not higher than the exposure value, institutions shall reduce the value of the credit protection calculated under paragraph 1 by 40 %;
where the amount that the protection provider has undertaken to pay is higher than the exposure value, the value of the credit protection shall be no higher than 60 % of the exposure value.
Where unfunded credit protection is denominated in a currency different from that in which the exposure is denominated, institutions shall reduce the value of the credit protection by the application of a volatility adjustment as follows:
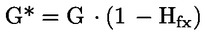
where:
| G* | = | the amount of credit protection adjusted for foreign exchange risk, |
| G | = | the nominal amount of the credit protection; |
| Hfx | = | the volatility adjustment for any currency mismatch between the credit protection and the underlying obligation determined in accordance with paragraph 4. |
Where there is no currency mismatch Hfx is equal to zero.
Institutions shall base the volatility adjustments for any currency mismatch on a 10 business day liquidation period, assuming daily revaluation, and shall calculate those adjustments based on the Supervisory Volatility Adjustments Approach as set out in Article 224. Institutions shall scale up the volatility adjustments in accordance with Article 226.