CRR › Article 239
Article 239 Valuation of protection
official text, verbatim
For transactions subject to funded credit protection under the Financial Collateral Simple Method, where there is a mismatch between the maturity of the exposure and the maturity of the protection, the collateral does not qualify as eligible funded credit protection.
For transactions subject to funded credit protection under the Financial Collateral Comprehensive Method, institutions shall reflect the maturity of the credit protection and of the exposure in the adjusted value of the collateral in accordance with the following formula:
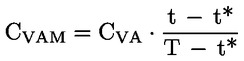
where:
| CVA | = | the volatility adjusted value of the collateral as specified in Article 223(2) or the amount of the exposure, whichever is lower; |
| t | = | the number of years remaining to the maturity date of the credit protection calculated in accordance with Article 238, or the value of T, whichever is lower; |
| T | = | the number of years remaining to the maturity date of the exposure calculated in accordance with Article 238, or five years, whichever is lower; |
| t* | = | 0,25. |
Institutions shall use CVAM as CVA further adjusted for maturity mismatch in the formula for the calculation of the fully adjusted value of the exposure (E*) set out in Article 223(5).
For transactions subject to unfunded credit protection, institutions shall reflect the maturity of the credit protection and of the exposure in the adjusted value of the credit protection in accordance with the following formula:
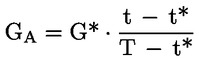
where:
| GA | = | G* adjusted for any maturity mismatch; |
| G* | = | the amount of the protection adjusted for any currency mismatch; |
| t | = | is the number of years remaining to the maturity date of the credit protection calculated in accordance with Article 238, or the value of T, whichever is lower; |
| T | = | is the number of years remaining to the maturity date of the exposure calculated in accordance with Article 238, or five years, whichever is lower; |
| t* | = | 0,25. |
Institutions shall use GA as the value of the protection for the purposes of Articles 233 to 236.