CRR › Article 280c
Article 280c Credit risk category add-on
official text, verbatim
For the purposes of paragraph 2, institutions shall establish the relevant credit reference entities of the netting set in accordance with the following:
there shall be one credit reference entity for each issuer of a reference debt instrument that underlies a single-name transaction allocated to the credit risk category; single-name transactions shall be assigned to the same credit reference entity only where the underlying reference debt instrument of those transactions is issued by the same issuer;
there shall be one credit reference entity for each group of reference debt instruments or single-name credit derivatives that underlie a multi-name transaction allocated to the credit risk category; multi-names transactions shall be assigned to the same credit reference entity only where the group of underlying reference debt instruments or single-name credit derivatives of those transactions have the same constituents.
For the purposes of Article 278, institution shall calculate the credit risk category add-on for a given netting set as follows:
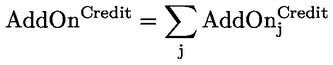
where:
| AddOnCredit | = | credit risk category add-on; |
| j | = | the index that denotes all the credit risk hedging sets established in accordance with point (c) of Article 277a(1) and with Article 277a(2) for the netting set; and |
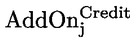 | = | the credit risk category add-on for hedging set j calculated in accordance with paragraph 3. |
Institutions shall calculate the credit risk category add-on for hedging set j as follows:
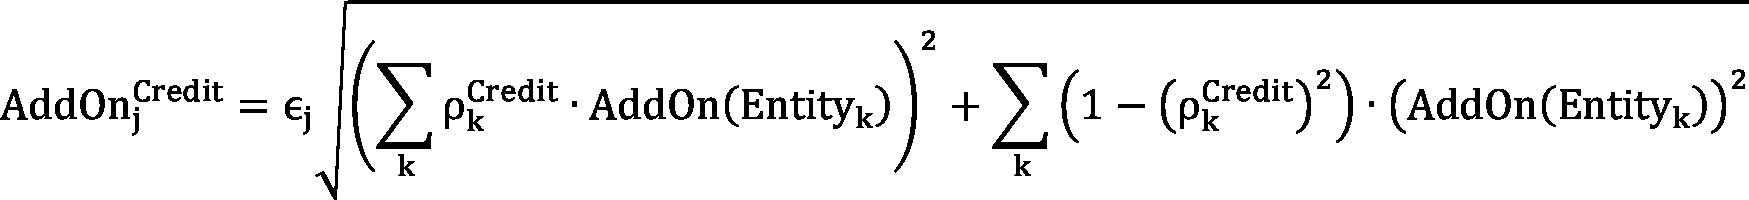
where:
| = | the credit risk category add-on for hedging set j; |
| єj | = | the hedging set supervisory factor coefficient of hedging set j determined in accordance with Article 280; |
| k | = | the index that denotes the credit reference entities of the netting set established in accordance with paragraph 1; |
 | = | the correlation factor of the credit reference entity k; where the credit reference entity k has been established in accordance with point (a) of paragraph 1, 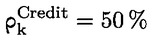 , where the credit reference entity k has been established in accordance with point (b) of paragraph 1, 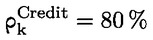 ; and |
| AddOn(Entityk) | = | the add-on for the credit reference entity k determined in accordance with paragraph 4. |
Institutions shall calculate the add-on for the credit reference entity k as follows:
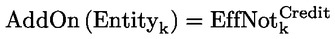
where:
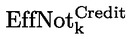 | = | the effective notional amount of the credit reference entity k calculated as follows: 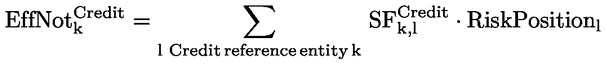 where: l = the index that denotes the risk position; and  = the supervisory factor applicable to the credit reference entity k calculated in accordance with paragraph 5. |
Institutions shall calculate the supervisory factor applicable to the credit reference entity k as follows:
for the credit reference entity k established in accordance with point (a) of paragraph 1,
shall be mapped to one of the six supervisory factors set out in Table 3 of this paragraph on the basis of an external credit assessment by a nominated ECAI of the corresponding individual issuer; for an individual issuer for which a credit assessment by a nominated ECAI is not available:
an institution using the approach referred to in Chapter 3 shall map the internal rating of the individual issuer to one of the external credit assessments;
an institution using the approach referred to in Chapter 2 shall assign
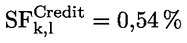
to that credit reference entity; however, where an institution applies Article 128 to risk weight counterparty credit risk exposures to that individual issuer,
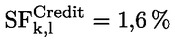
shall be assigned to that credit reference entity;
for the credit reference entity k established in accordance with point (b) of paragraph 1:
where a risk position l assigned to the credit reference entity k is a credit index listed on a recognised exchange,
shall be mapped to one of the two supervisory factors set out in Table 4 of this paragraph on the basis of the credit quality of the majority of its individual constituents;
where a risk position l assigned to the credit reference entity k is not referred to in point (i) of this point,
shall be the weighted average of the supervisory factors mapped to each constituent in accordance with the method set out in point (a), where the weights are defined by the proportion of notional of the constituents in that position.
Table 3
| Credit quality step | Supervisory factor for single-name transactions |
| 1 | 0,38 % |
| 2 | 0,42 % |
| 3 | 0,54 % |
| 4 | 1,06 % |
| 5 | 1,6 % |
| 6 | 6,0 % |
Table 4
| Dominant credit quality | Supervisory factor for quoted indices |
| Investment grade | 0,38 % |
| Non-investment grade | 1,06 % |