CRR › Article 280d
Article 280d Equity risk category add-on
official text, verbatim
For the purposes of paragraph 2, institutions shall establish the relevant equity reference entities of the netting set in accordance with the following:
there shall be one equity reference entity for each issuer of a reference equity instrument that underlies a single-name transaction allocated to the equity risk category; single-name transactions shall be assigned to the same equity reference entity only where the underlying reference equity instrument of those transactions is issued by the same issuer;
there shall be one equity reference entity for each group of reference equity instruments or single-name equity derivatives that underlie a multi-name transaction allocated to the equity risk category; multi-names transactions shall be assigned to the same equity reference entity only where the group of underlying reference equity instruments or single-name equity derivatives of those transactions, as applicable, has the same constituents.
For the purposes of Article 278, institutions shall calculate the equity risk category add-on for a given netting set as follows:
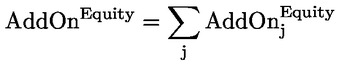
where:
| AddOnEquity | = | the equity risk category add-on; |
| j | = | the index that denotes all the equity risk hedging sets established in accordance with point (d) of Article 277a(1) and Article 277a(2) for the netting set; and |
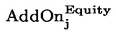 | = | the equity risk category add-on for hedging set j calculated in accordance with paragraph 3. |
Institutions shall calculate the equity risk category add-on for hedging set j as follows:
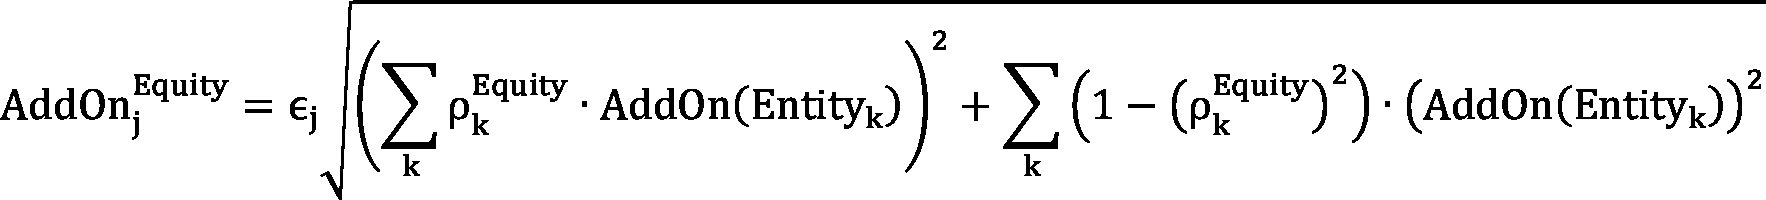
where:
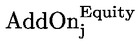 | = | the equity risk category add-on for hedging set j; |
| єj | = | the hedging set supervisory factor coefficient of hedging set j determined in accordance with Article 280; |
| k | = | the index that denotes the equity reference entities of the netting set established in accordance with paragraph 1; |
 | = | the correlation factor of the equity reference entity k; where the equity reference entity k has been established in accordance with point (a) of paragraph 1, 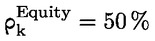 ; where the equity reference entity k has been established in accordance with point (b) of paragraph 1, 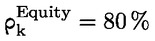 ; and |
| AddOn(Entityk) | = | the add-on for the equity reference entity k determined in accordance with paragraph 4. |
Institutions shall calculate the add-on for the equity reference entity k as follows:
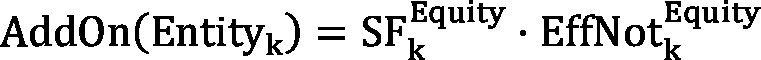
where:
| AddOn(Entityk) | = | the add-on for the equity reference entity k; |
 | = | the supervisory factor applicable to the equity reference entity k; where the equity reference entity k has been established in accordance with point (a) of paragraph 1, 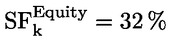 ; where the equity reference entity k has been established in accordance with point (b) of paragraph 1, 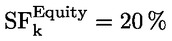 ; and |
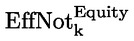 | = | the effective notional amount of the equity reference entity k calculated as follows: 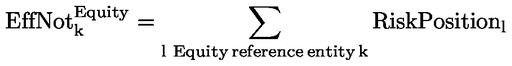 where: l = the index that denotes the risk position. |