CRR › Article 281
Article 281 Calculation of the exposure value
official text, verbatim
Institutions shall calculate a single exposure value at netting set level in accordance with Section 3, subject to paragraph 2 of this Article.
The exposure value of a netting set shall be calculated in accordance with the following requirements:
institutions shall not apply the treatment referred to in Article 274(6);
by way of derogation from Article 275(1), for netting sets that are not referred to in Article 275(2), institutions shall calculate the replacement cost in accordance with the following formula:
RC = max{CMV, 0}
where:
| RC | = | the replacement cost; and |
| CMV | = | the current market value. |
by way of derogation from Article 275(2) of this Regulation, for netting sets of transactions: that are traded on a recognised exchange; that are centrally cleared by a central counterparty authorised in accordance with Article 14 of Regulation (EU) No 648/2012 or recognised in accordance with Article 25 of that Regulation; or for which collateral is exchanged bilaterally with the counterparty in accordance with Article 11 of Regulation (EU) No 648/2012, institutions shall calculate the replacement cost in accordance with the following formula:
RC = TH + MTA
where:
| RC | = | the replacement cost; |
| TH | = | the margin threshold applicable to the netting set under the margin agreement below which the institution cannot call for collateral; and |
| MTA | = | the minimum transfer amount applicable to the netting set under the margin agreement; |
by way of derogation from Article 275(3), for multiple netting sets that are subject to a margin agreement, institutions shall calculate the replacement cost as the sum of the replacement cost of each individual netting set, calculated in accordance with paragraph 1 as if they were not margined;
all hedging sets shall be established in accordance with Article 277a(1);
institutions shall set to 1 the multiplier in the formula that is used to calculate the potential future exposure in Article 278(1), as follows:
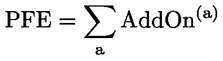
where:
| PFE | = | the potential future exposure; and |
| AddOn(a) | = | the add-on for risk category a; |
by way of derogation from Article 279a(1), for all transactions, institutions shall calculate the supervisory delta as follows:
| δ = |  | + 1 where the transaction is a long position in the primary risk driver |
| – 1 where the transaction is a short position in the primary risk driver |
where:
| δ | = | the supervisory delta; |
the formula referred to in point (a) of Article 279b(1) that is used to compute the supervisory duration factor shall read as follows:
supervisory duration factor = E – S
where:
| E | = | the period between the end date of a transaction and the reporting date; and |
| S | = | the period between the start date of a transaction and the reporting date; |
the maturity factor referred to in Article 279c(1) shall be calculated as follows:
for transactions included in netting sets referred to in Article 275(1), MF = 1;
for transactions included in netting sets referred to in Article 275(2) and (3), MF = 0,42;
the formula referred to in Article 280a(3) that is used to calculate the effective notional amount of hedging set j shall read as follows:
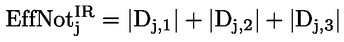
where:
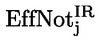 | = | the effective notional amount of hedging set j; and |
| Dj,k | = | the effective notional amount of bucket k of hedging set j; |
the formula referred to in Article 280c(3) that is used to calculate the credit risk category add-on for hedging set j shall read as follows:
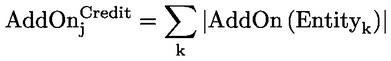
where:
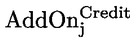 | = | the credit risk category add-on for hedging set j; and |
| AddOn(Entityk) | = | the add-on for the credit reference entity k; |
the formula referred to in Article 280d(3) that is used to calculate the equity risk category add-on for hedging set j shall read as follows:
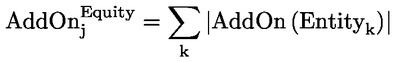
where:
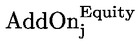 | = | the equity risk category add-on for hedging set j; and |
| AddOn(Entityk) | = | the add-on for the credit reference entity k; |
the formula referred to in Article 280e(4) that is used to calculate the commodity risk category add-on for hedging set j shall read as follows:
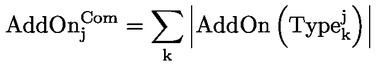
where:
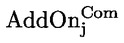 | = | the commodity risk category add-on for hedging set j; and |
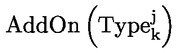 | = | the add-on for the commodity reference type k. |