CRR › Article 325h
Article 325h Aggregation of risk-class specific own funds requirements for delta, vega and curvature risks
official text, verbatim
Institutions shall aggregate risk-class specific own funds requirements for delta, vega and curvature risks in accordance with the process set out in paragraphs 2, 3 and 4.
The process to calculate the risk-class specific own funds requirements for delta, vega and curvature risks described in Articles 325f and 325g shall be performed three times per risk class, each time using a different set of correlation parameters ρkl (correlation between risk factors within a bucket) and γbc (correlation between buckets within a risk class). Each of those three sets shall correspond to a different scenario, as follows:
the medium correlations scenario, whereby the correlation parameters ρkl and γbc remain unchanged from those specified in Section 6;
the high correlations scenario, whereby the correlation parameters ρkl and γbc that are specified in Section 6 shall be uniformly multiplied by 1,25, with ρkl and γbc subject to a cap at 100 %;
the ‘low correlations’ scenario, whereby the correlation parameters ρkl and γbc that are specified in Section 6 shall be replaced by 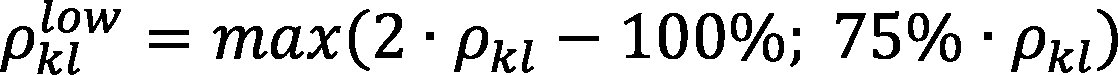 and
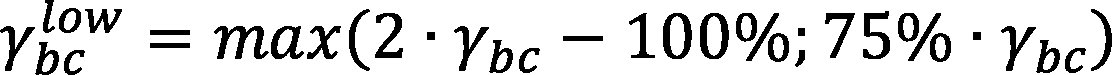 , respectively.
Institutions shall calculate the sum of the delta, vega and curvature risk-class specific own funds requirements for each scenario to determine three scenario-specific, own funds requirements.
The own funds requirement under the sensitivities-based method shall be the highest of the three scenario-specific own funds requirements referred to in paragraph 3.