CRR › Article 325r
Article 325r Delta risk sensitivities
official text, verbatim
Institutions shall calculate delta general interest rate risk (GIRR) sensitivities as follows:
the sensitivities to risk factors consisting of risk-free rates shall be calculated as follows:
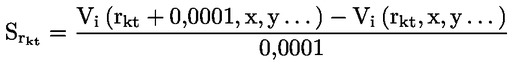
where:
 | = | the sensitivities to risk factors consisting of risk-free rates; |
| rkt | = | the rate of a risk-free curve k with maturity t; |
| Vi (.) | = | the pricing function of instrument i; and |
| x,y | = | risk factors other than rkt in the pricing function Vi; |
the sensitivities to risk factors consisting of inflation risk and cross-currency basis shall be calculated as follows:
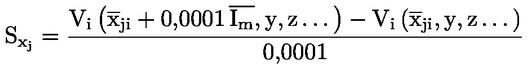
where:
 | = | the sensitivities to risk factors consisting of inflation risk and cross-currency basis; |
 | = | a vector of m components representing the implied inflation curve or the cross-currency basis curve for a given currency j with m being equal to the number of inflation or cross-currency related variables used in the pricing model of instrument i; |
 | = | the unity matrix of dimension (1 × m); |
| Vi (.) | = | the pricing function of the instrument i; and |
| y, z | = | other variables in the pricing model. |
Institutions shall calculate the delta credit spread risk sensitivities for all securitisation and non-securitisation positions as follows:
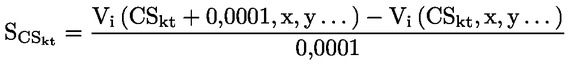
where:
 | = | the delta credit spread risk sensitivities for all securitisation and non-securitisation positions; |
| cskt | = | the value of the credit spread rate of an issuer j at maturity t; |
| Vi (.) | = | the pricing function of instrument i; and |
| x,y | = | risk factors other than cskt in the pricing function Vi. |
Institutions shall calculate delta equity risk sensitivities as follows:
the sensitivities to risk factors consisting of equity spot prices shall be calculated as follows:
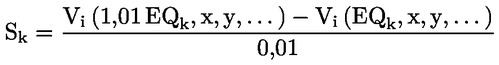
where:
| sk | = | the sensitivities to risk factors consisting of equity spot prices; |
| k | = | a specific equity security; |
| EQk | = | the value of the spot price of that equity security; |
| Vi (.) | = | the pricing function of instrument i; and |
| x,y | = | risk factors other than EQk in the pricing function Vi; |
the sensitivities to risk factors consisting of equity repo rates shall be calculated as follows:
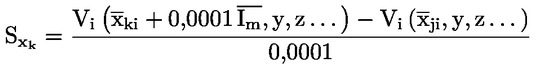
where:
 | = | the sensitivities to risk factors consisting of equity repo rates; |
| k | = | the index that denotes the equity; |
 | = | a vector of m components representing the repo term structure for a specific equity k with m being equal to the number of repo rates corresponding to different maturities used in the pricing model of instrument i; |
| = | the unity matrix of dimension (1 · m); |
| Vi (.) | = | the pricing function of the instrument i; and |
| y,z | = | risk factors other than in the pricing function Vi. |
Institutions shall calculate the delta commodity risk sensitivities to each risk factor k as follows:
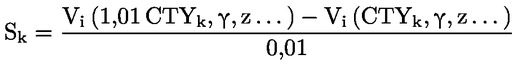
where:
| sk | = | the delta commodity risk sensitivities; |
| k | = | a given commodity risk factor; |
| CTYk | = | the value of risk factor k; |
| Vi (.) | = | the pricing function of instrument i; and |
| y, z | = | risk factors other than CTYk in the pricing model of instrument i. |
Institutions shall calculate the delta foreign exchange risk sensitivities to each foreign exchange risk factor k as follows:
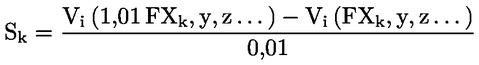
where:
| sk | = | the delta foreign exchange risk sensitivities; |
| k | = | a given foreign exchange risk factor; |
| FXk | = | the value of the risk factor; |
| Vi (.) | = | the pricing function of instrument i; and |
| y, z | = | risk factors other than FXk in the pricing model of instrument i. |