CRR › Article 325s
Article 325s Vega risk sensitivities
official text, verbatim
Institutions shall calculate the vega risk sensitivity of an option to a given risk factor k as follows:
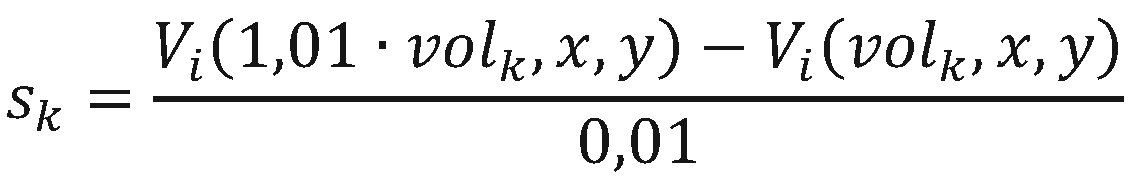
where:
| sk | = | the vega risk sensitivity of an option; |
| k | = | a specific vega risk factor, consisting of an implied volatility; |
| volk | = | the value of that risk factor, which should be expressed as a percentage; and |
| x,y | = | risk factors other than volk in the pricing function Vi. |
In the case of risk classes where vega risk factors have a maturity dimension, but where the rules to map the risk factors are not applicable because the options do not have a maturity, institutions shall map those risk factors to the longest prescribed maturity. Those options shall be subject to the residual risks add-on.
In the case of options that do not have a strike or barrier and options that have multiple strikes or barriers, institutions shall apply the mapping to strikes and maturity used internally by the institution to price the option. Those options shall also be subject to the residual risks add-on.
Institutions shall not calculate the vega risk for securitisation tranches included in the ACTP, as referred to in Article 325(6), (7) and (8), that do not have an implied volatility. Own funds requirements for delta and curvature risk shall be computed for those securitisation tranches.