CRR › Article 325y
Article 325y Calculation of the own funds requirements for the default risk
official text, verbatim
Net JTD amounts, irrespective of the type of counterparty, shall be multiplied by the default risk weights that correspond to their credit quality, as specified in Table 2:
Table 2
| Credit quality category | Default risk weight |
| Credit quality step 1 | 0,5 % |
| Credit quality step 2 | 3 % |
| Credit quality step 3 | 6 % |
| Credit quality step 4 | 15 % |
| Credit quality step 5 | 30 % |
| Credit quality step 6 | 50 % |
| Unrated | 15 % |
| Defaulted | 100 % |
Exposures which would receive a 0 % risk-weight under the Standardised Approach for credit risk in accordance with Chapter 2 of Title II shall receive a 0 % default risk weight for the own funds requirements for the default risk.
The weighted net JTD shall be allocated to the following buckets: corporates, sovereigns, and local governments/municipalities.
Weighted net JTD amounts shall be aggregated within each bucket, in accordance with the following formula:
DRCb = max {(Σi ∈ long RWi · net JTDi) – WtS · (Σi ∈ short RWi · |net JTDi|); 0}
where:
| DRCb | = | the own funds requirement for the default risk for bucket b; |
| i | = | the index that denotes an instrument belonging to bucket b; |
| RWi | = | the risk weight; and |
| WtS | = | a ratio recognising a benefit for hedging relationships within a bucket, which shall be calculated as follows: 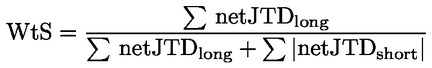 |
For the purposes of calculating the DRCb and the WtS, the long positions and short positions shall be aggregated for all positions within a bucket, regardless of the credit quality step to which those positions are allocated, to produce the bucket-specific own funds requirements for the default risk.
The final own funds requirement for the default risk for non-securitisations shall be calculated as the simple sum of the bucket-level own funds requirements.
For the purposes of this Article, an exposure shall be assigned the credit quality category corresponding to the credit quality category that it would be assigned under the standardised approach for credit risk set out in Title II, Chapter 2.